Keeping Canada’s financial services on the cutting edge: Q&A with Alex Vronces
Featuring
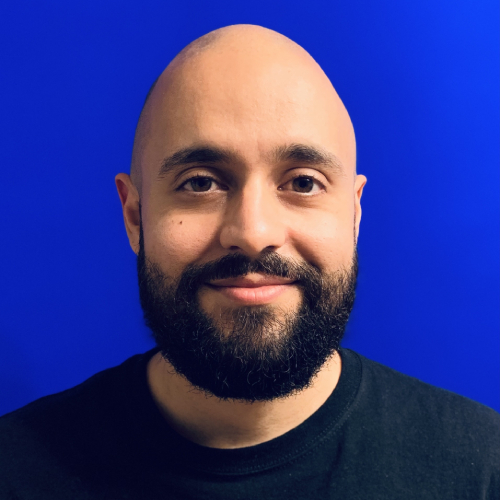
Alex Vronces, Executive Director, Fintechs Canada
Read commentary from our lawyers for the latest legal and industry trends in our article “The future of payments in Canada: are we finally making progress?” And for more industry insights, read our in-depth Q&A featuring Andrew Graham, Co-founder and CEO, Borrowell.
How confident are you that the government will achieve having a fully implemented open banking framework by 2025? What do you think are the biggest stumbling blocks to achieving this goal?
The last time the government said it was going to implement consumer-driven banking by no later than January 2023, the way I interpreted it was that they were going to give the Big Five carte blanche to work together and stand something up. When you considered all that had to be done, and how little had been done, this was the most plausible interpretation. It’s hard for me to imagine how the government would have been able to accomplish that timeline without looking to the industry.
We’re in a different world now. As the federal government’s open banking lead, Abraham Tachjian did a lot of work to put together a consumer-driven banking instruction manual, which was delivered to the Minister of Finance. Most of the big questions have been answered, but a few remain. For example, there’s one about governance. The government said it would mandate a government-led entity to oversee the system. Who is that entity? Is it new or existing? How is it going to be set up for success? How much money will that cost?
The government’s goal is certainly possible. I’d go further and say it’s plausible if and only if we take the next logical step after the policy statement, which is to implement it. Implicit in that policy statement is the government has made many decisions about big things, which means there’s little left to do.
The success of an open banking framework is often noted as being dependent on the establishment of a Real-Time Rail for real-time payments. Do you think this is the case? Is there an advantage to having an open banking framework without an RTR?
There are many use cases that don’t require a real-time payment system to work. Reporting rent payments to build your credit score. Budgeting. More automation around bookkeeping and reconciliation. The list goes on.
But a more modern payments infrastructure, which allows for secure and seamless third-party payment initiation, would expand the scope of innovation. For example, imagine an app that not only budgets for you but also manages all your bill payments for you in a way that maximizes the cash you have on hand.
Good regulation is good, but good regulation with good technological infrastructure is even better. Open banking, by itself, will benefit Canadians. But open banking and a real-time, data-rich payment system? That’s going to mean more.
The federal government has begun opening up the membership in Payments Canada by amending the Canadian Payments Act. The intent seems to be to allow all payment service providers that are subject to the Retail Payments Activities Act to be eligible for membership. Is that realistic?
The main reason for joining Payments Canada is to directly access their payment systems. But direct access to payment systems is not for everyone in the payments value chain, just like how being a farmer is not for everyone in the agricultural value chain. We also need the suppliers of capital, equipment, the distributors, and the storefronts. The same is true of payments. Everyone will do what they have a comparative advantage in—and Canada will be better for it.
Right now, there are some companies for whom it makes sense to directly access payment systems. Take Wise, a global fintech company, as one example. In the United Kingdom, when they got direct access to the faster payment system, they were able to immediately reduce costs by 20% and the time it takes their customers to move money to seconds.
So, some payment service providers will join, and others will not. It’s hard to predict who will and who won’t because we still need more details around what the RTR is, what it will do, and how much it will cost to use.
What kind of impact do you expect that these various regulatory changes will have on the fintech sector?
It depends on the time horizon. In the short term, I think it will reduce the number of fintechs more than it will increase it. More regulation will increase the cost of doing business, and so we should expect to see people try to get gobbled up by a bigger player or drop out of the market entirely. In the long run, I think we’ll see more growth in fintech. While regulation increases the cost of doing business, it also unlocks opportunity. Entrepreneurs with more regulatory certainty will find a way to thrive by outdoing their competitors.
What are the biggest challenges currently facing the fintech sector?
I’m partial to the idea that the biggest challenge in Canada is our cultural context. Consider that the U.S. isn’t known for having a world-class regulatory system to promote innovation in the financial sector, and yet the U.S. has many fintech success stories. Compared to us, the U.S. has a bigger customer base, more money-chasing ideas, and greater access to the most talented people in the world. How did they get that way? It’s possible they’re more risk-loving than we are. Perhaps Americans are more comfortable with people trying something extremely ambitious and failing, whereas Canadians are happier to bask in the glory of old success than risk undoing it, like surviving the financial crisis of the 2000s. The former culture will make bolder and faster progress on whatever it does than the latter.
What would Canada need to do to catch up to other G7 countries? Do you think we can even catch up?
We need to change the culture. To do that, we need louder and prouder fintech success stories. At the margin, smarter regulation will help. But it won’t take us all the way there. It will simply let us try to compete. We need to raise the status of grand ambition so more people try to do really hard things without shame. When they fail, they’ll try again. When they succeed, they’ll inspire the next generation of founders to mimic their grand ambition. It’s the start of a new and virtuous cycle to break the pattern of an old and not-so-virtuous one.
Looking at what is happening in the regulatory space, what would be your three top recommendations for fintechs?
I have just one: dispel yourself of the myth that you should focus exclusively on building great products, and you can afford to neglect your relationship with the government. The market for financial services is not like the market for software. Permissionless innovation works in the latter but not in the former. Financial services is one of the most heavily regulated markets, and so nothing happens that isn’t ordained by the government. Even if you’re not regulated by the government, your partner bank is, and your bank is required by the government to manage the risks you pose. The rules are also always changing, and so there’s always a risk that your competitors are using the law as a cudgel. There’s a certain amount of facetime you need with the government to simply protect yourself. Recall the old saying that if you’re not at the table, then you’re on the menu.
What’s your 10-year forecast for the fintech sector?
Whatever the prediction markets, if there are any, are saying.
Alex Vronces is the executive director of Fintechs Canada, the unified voice of Canadian fintech. Fintechs Canada is an industry association of Canada's most innovative financial technology companies. Alex has also worked as a policy wonk at Payments Canada, the Canadian Chamber of Commerce, and dabbled in journalism.
Le mois dernier, le Canada a publié sa première Stratégie industrielle de défense (la Stratégie), qui souligne l’engagement du Canada à développer une base industrielle de défense solide et à stimuler la croissance économique. Ces efforts pourraient aussi comprendre le renforcement de l’état de préparation à la biodéfense et aux contre-mesures médicales, ce qui pourrait constituer des débouchés pour le secteur canadien des sciences de la vie en raison de l’importance accordée aux capacités nationales en ce sens et de la nécessité d’atténuer les risques d’urgences sanitaires.
Développement de contre-mesures médicales au Canada
Comme indiqué dans les bulletins précédents, le quatrième pilier de la Stratégie est axé sur la « sécurisation des chaînes d’approvisionnement pour les intrants et les biens clés » par le renforcement de la production nationale et le stockage de ressources. L’accent est mis tout particulièrement sur les contre-mesures médicales, en précisant que nos « alliés ont établi un lien explicite entre l’état de préparation à la biodéfense et aux contre-mesures médicales et leur sécurité économique et nationale, en élaborant de nouvelles stratégies et de nouveaux mécanismes pour faire progresser ces travaux ». Les contre-mesures médicales désignent divers produits réglementés pouvant être utilisés pour protéger la population lors d’une situation d’urgence de grande ampleur, comme l’éclosion d’une maladie ou une attaque impliquant des armes chimiques, biologiques ou nucléaires. Il peut s’agir de vaccins, de médicaments thérapeutiques et produits biologiques, de dispositifs de tests diagnostiques, des équipements de protection individuelle ou industrielle, et d’autres dispositifs médicaux. Les contre-mesures médicales sont essentielles à la réduction et à l’atténuation des dommages lors d’une urgence de santé publique.
Exploiter les voies réglementaires mises en place lors de la pandémie de COVID-19
Pendant et après la pandémie de COVID-19, le Canada a mis en place plusieurs nouvelles voies réglementaires comme mécanismes d’accélération des approbations de produits médicaux, ce qui pourrait offrir au gouvernement des options pour déployer des contre-mesures médicales afin de faire face aux risques pour la santé publique. Au début de la pandémie, Santé Canada a émis diverses ordonnances provisoires pour permettre l’importation et la vente de médicaments et de dispositifs médicaux qui n’avaient pas eu l’approbation des voies réglementaires traditionnelles. Or, Santé Canada a plutôt fait confiance aux voies d’approbation réglementaire et de l’exemption de certaines exigences en homologation de produits des pays impliqués dans la transaction. Beaucoup de ces règles provisoires ont depuis été officiellement intégrées à la réglementation en vertu de la Loi sur les aliments et drogues et ont été appliquées bien après la COVID-19. Conformément au Règlement sur les aliments et drogues, Santé Canada tient à jour la Liste des maladies qui menacent la santé publique et utilisera une procédure d’autorisation modifiée pour les médicaments d’urgence de santé publique pouvant traiter les affections figurant sur la liste. De même, le Règlement sur les instruments médicaux a établi une liste d’instruments médicaux répondant à un besoin urgent de santé publique, ce qui permet à Santé Canada d’autoriser la commercialisation de ces instruments de manière accélérée. Ces outils réglementaires sont utilisés automatiquement quand une situation médicale présente un grand risque pour la santé publique au Canada et nécessite une action immédiate pour contrer ce risque.
Le rôle de la Stratégie dans le renforcement du régime réglementaire de la santé au Canada
La stratégie prévoit que le Canada adoptera une approche proactive en matière de planification en amont des crises sanitaires. Le gouvernement entend s’assurer que les produits médicaux sont déjà disponibles au Canada afin qu’ils puissent être distribués rapidement en cas d’urgence. D’autres modifications récentes au Règlement sur les aliments et drogues permettent de prépositionner au Canada tous les médicaments d’urgence en santé publique, ce qui signifie qu’ils peuvent être importés dans des installations d’entreposage canadiennes avant que leur mise sur le marché n’ait été autorisée. La Stratégie s’appuie sur ces fondements, en faisant référence à l’organisme existant Préparation aux crises sanitaires Canada (PCSC), un organisme opérationnel spécial au sein d’Innovation, Sciences et Développement économique Canada (ISDE), et à un nouveau Fonds des sciences de la vie, lesquels « collaborent avec des partenaires internationaux et de soutenir l’élaboration et la production de contre-mesures médicales ». PCSC supervise la Stratégie en matière de biofabrication et de sciences de la vie du Canada, qui vise à développer un secteur national des sciences de la vie fort et compétitif doté de capacités de biofabrication de pointe, en mettant l’accent sur la capacité à se préparer et à faire face aux futures priorités et crises sanitaires. Dans cette optique, il y aura des occasions pour les fabricants de nouer des collaborations de recherche et des accords commerciaux ou d’approvisionnement liés aux contre-mesures médicales financées par des programmes fédéraux.
Étroitement lié aux capacités nationales, le pilier III de la stratégie implique « Investissement ciblé pour renforcer un secteur canadien de la défense novateur », avec la promesse que le gouvernement fédéral « soutiendr[a] la recherche et le développement, protéger[a] la propriété intellectuelle, soutiendr[a] les petites et moyennes entreprises, investir[a] dans les compétences et la formation, et encourager[a] les exportations afin de créer un secteur de la défense agile et concurrentiel à l’échelle mondiale ». La nécessité de favoriser le développement de la propriété intellectuelle (PI) et la conservation des droits du Canada est mentionnée à plusieurs reprises dans la Stratégie. Par exemple, la Stratégie prévoit l’établissement de partenariats officiels avec l’industrie canadienne qui « [assureront] la propriété et le contrôle nationaux de la propriété intellectuelle (PI) et des capacités essentielles. » La Stratégie reconnaît l’immense talent des établissements canadiens et la précieuse recherche qui y est menée actuellement et qui est déjà financée par des subventions de recherche d’organismes tels que le Conseil de recherches en sciences naturelles et en génie et les Instituts de recherche en santé du Canada, et fait aussi référence à l’engagement de 1,6 milliard de dollars pour de nouveaux fonds de recherche dans le budget de 2025. Cette prise de conscience de la nécessité de promouvoir et de soutenir l’innovation au Canada laisse présager des possibilités de financement, notamment dans les domaines où le Canada accuse un retard en matière de production nationale et où des engagements d’investissement et de fabrication au Canada peuvent être pris.
Prochaines étapes
Dans les prochains mois, nous prévoyons que le gouvernement du Canada publiera d’autres directives et des mesures de suivi. L’équipe de défense des conservateurs poursuivra sa couverture de perspectives sur la défense au Canada en publiant une analyse supplémentaire pour donner des précisions sur l’incidence de la Stratégie sur de multiples secteurs.
Tags