The rise of voluntary carbon markets
Authors
 Tyson Dyck
Henry Ren
 Emily Stewart
The voluntary carbon markets (VCMs) are poised for explosive growth in 2022. At the conclusion of COP26 in Glasgow, 632 of the world’s largest 2000 public companies by revenue had announced plans to achieve Net Zero greenhouse gas (GHG) emissions1. Although not all of these companies will use carbon credits to help achieve their decarbonization goals, many will. Over 40% of these firms plan to use offsetting as a strategy to achieve their Net Zero commitments, with few companies ruling out this possibility2. According to the World Bank, this growth “in voluntary corporate commitments is the main driving force behind increased carbon credit demand”3.
Current state of the voluntary carbon market
For years, the global carbon markets were dominated by compliance credits—credits that can be used for compliance with domestic or international emissions reduction regimes. For example, most of the early trading in carbon offsets was in Certified Emissions Reductions under the Clean Development Mechanism (CDM), which were primarily used for compliance with the Kyoto Protocol4.
In contrast, voluntary credits are issued in respect of projects registered with voluntary emissions reduction programs, such as the Verified Carbon Standard (VCS) or the Gold Standard. These credits are not used for compliance with a regulatory regime, but rather to support voluntary corporate GHG reduction commitments or claims.
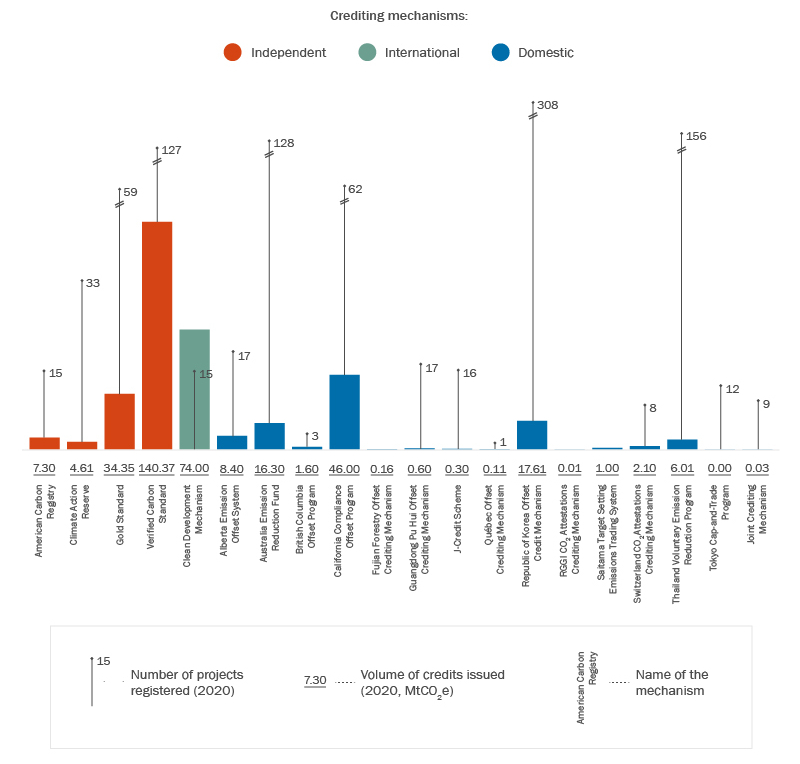
In recent years, the VCMs have grown rapidly as more of the world’s largest companies commit to achieving Net Zero—to balance their GHG emissions with GHG removals over a specified time period5. In 2020, the VCS alone registered 127 projects and issued credits representing 140.37 megatonnes of carbon dioxide equivalent (MtCO2e). In contrast, the CDM registered 15 projects and issued 74 MtCO2e in credits.
Figure 1: Use of carbon crediting schemes6
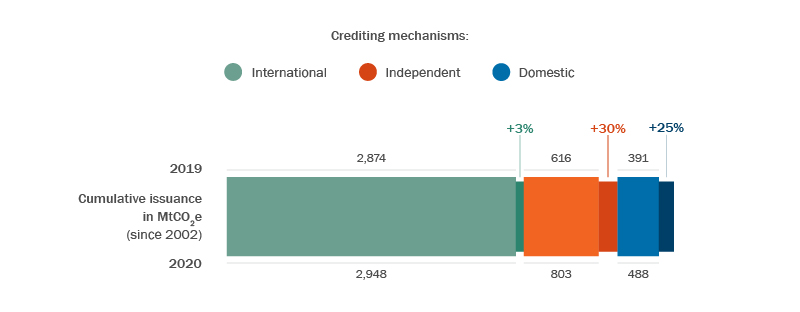
In fact, between 2019 and 2020, credit issuances by the VCS and other “independent” VCMs outpaced the growth in “domestic” and “international” compliance credit regimes, as seen in the following figure.
Figure 2: Crediting scheme use breakdown
Predicted growth of the voluntary carbon markets
The rapid growth in the VCMs will accelerate in the coming years, especially as more companies announce Net Zero commitments. As one telling example, Shell has announced its intention to purchase carbon credits representing 120 million MtCO2e annually by 2030—a volume that exceeds the total size of all voluntary markets in 20197. The Net-Zero Banking Alliance, comprised of institutions representing over 40% of global banking assets, has also committed to aligning its lending and investment portfolios with Net Zero emissions by 2050, which in many cases will involve the purchase of carbon credits8. According to some models, the market for voluntary carbon credits is expected to increase fifteenfold by 2030 and one hundredfold by 20509.
The value of the voluntary markets is estimated to grow in parallel to this demand. In 2020, the value of the VCMs was estimated to be approximately $300 million. That value is expected to grow to anywhere between $5 and $180 billion annually by 203010. The chief executive of the Institute of International Finance has predicted the market to be worth approximately $100 billion a year by 205011.
Potential issues in scaling the voluntary carbon markets
Such a rapid scaling of the VCMs will present challenges. First, there remains an open debate over whether and to what extent companies looking to achieve their Net Zero commitments should use carbon credits at all. Historically, concerns have been raised over the environmental integrity of certain offset credits. For example, in the early days of the CDM, market observers found that some credits were awarded to projects that did not achieve meaningful emissions. A leading project developer explained to us the growing pains evident in the CDM’s early days: “[t]here used to be too little scrutiny of projects [and] a lot of projects that got through were undeserving”12. This sentiment was relatively widespread; some criticized the CDM as a subsidy program for activities that, in certain cases, did not ultimately produce real, verifiable and additional emissions reductions13.
Although the environmental integrity of the carbon markets has improved over the years, these concerns still linger and support the view that only high-quality credits, which reflect actual emissions reductions, should be used to balance corporate carbon accounting books. This has led organizations like the Task Force on Scaling Voluntary Carbon Markets (the Taskforce), the Science-based Targets Initiative and the Oxford Principles for Net Zero Aligned Carbon Offsetting to recommend that corporations should first prioritize their own emissions, and use carbon credits only as a supplementary strategy to achieve Net Zero14.
Another challenge in scaling the VCMs is how to get enough high-quality credits to market in time to meet demand. This has been another recurring issue in carbon markets. In the early days of the CDM, the system was flooded with new offset projects. As a member of the CDM’s Registration and Issuance Team described that time to us:
[T]here would be a permanent strain in the first years as everybody scrambled to keep up with the workload, which, of course, relates to all the players in the system—the regulators, the validators, even some of the project developers. The CDM grew very quickly and maybe a bit too quickly15.
The carbon markets, including the VCMs, have learned from those early experiences, and many programs now generate higher quality credits more efficiently than the CDM did in its first few years. In addition, market actors—including project proponents, program administrators and buyers—generally recognize that carbon credits are only helpful in achieving Net Zero targets if they have environmental integrity. Otherwise, they do not function to balance corporate emissions, but instead can expose those companies to claims of “carbon washing”. As a result, many companies prefer to buy high-quality carbon removal credits—credits representing carbon dioxide that is removed from the atmosphere and stored either in the biosphere (e.g., in forests, soil or the oceans) or in geological formations, rather than credits representing avoided emissions.
Companies looking to acquire only carbon removal credits may face greater procurement challenges. For example, in 2020, Microsoft and financial services firm Stripe solicited carbon sequestration proposals. Microsoft received 189 proposals representing 154 MtCO2e removal, but only 55 MtCO2e were immediately available and only 2 MtCO2e met Microsoft’s criteria for high-quality carbon removal projects. Meanwhile, Stripe received 47 proposals but only 0.024 MtCO2e met the company’s stringent requirements for carbon removals16.
According to some estimates, the demand for voluntary carbon credits to achieve a 1.5-2 degree compliant climate scenario may require up to 7-13 gigatonnes of CO2e removals or storage each year by 205017.
McKinsey estimated there may be approximately 8-12 gigatonnes available, but certain supply issues may impede the flow of credits into market. The availability of verifiers, the geographic concentration of credits and financing challenges may all restrict the availability of high-quality credits.
Future evolution of the voluntary carbon markets
Promising efforts are underway to harmonize and scale up the currently fragmented VCMs to address growing demand. In particular, the Taskforce has announced the formation of an independent governance body that would administer Core Carbon Principles (CCPs)18, a standardized set of environmental integrity standards that would be used to evaluate carbon credits. Once certified against the CCPs, carbon credits could be given attribute tags, indicating, as applicable, the credit type (e.g., avoidance or removal), the method of carbon sequestration or storage, whether any corresponding adjustments were made when the credit was sold from its originating jurisdiction and whether the credit involved any co-benefits (e.g., for the local community or biodiversity)19. Credits with CCP tags could be bought and sold through standardized exchange-traded contracts, which could be priced based on the underlying attributes.
Although significant work remains to implement this type of system, it does offer a promising solution to unify what remains a fragmented and relatively early-stage market in the face of quickly accelerating demand.
- Net Zero Tracker, Table of 2,000 Largest Publicly-Traded Companies. Available here. This total has subsequently risen to 706.
- Net Zero Tracker, Post-COP26 Snapshot. Available here.
- World Bank, State and Trends of Carbon Pricing 2021 (May 2021), p. 45. Available here.
- Id., p. 78.
- Definitions of Net Zero emissions vary, but many organizations adopt that of the Intergovernmental Panel on Climate Change (available here), which defines “net zero emissions” as being “achieved when anthropogenic emissions of greenhouse gases to the atmosphere are balanced by anthropogenic removals over a specified period”.
- Notes: (1) Data for Spain FES-CO2 program and Taiwan GHG Offset Management program was insufficient to present annual changes to credits issued and registered activities. Also, data for the crediting mechanism in Colombia was not available at the time of publication. These crediting mechanisms are omitted from the figure. (2) In addition, the following crediting mechanisms did not register any new projects or issue credits in 2020 and were therefore excluded from the graph: Joint Implementation Mechanism, Beijing Forestry Offset Mechanism, Beijing Parking Offset Crediting Mechanism, China GHG Voluntary Emission Reduction Program, Fujian Forestry Offset Crediting Mechanism, Saitama Forest Absorption Certification System, and South Africa Crediting Mechanism.
- Supra at note 3, p. 45.
- UN Environmental Programme Finance Initiative, Net-Zero Banking Alliance. Website available here.
- Taskforce on Scaling Voluntary Carbon Markets, Phase 1 Final Report (January 2021), p. 55. Available here.
- McKinsey & Company, Putting Carbon Markets to Work on the Path to Net Zero (October 2021), p. 13. Available here.
- CNBC, IIF sees huge potential for voluntary carbon credits, predicts $100 billion a year market by 2050 (July 8, 2021). Available here.
- Tyson Dyck, Enforcing Environmental Integrity: Emissions Auditing and the Extended Arm of the Clean Development Mechanism, Columbia Journal of Environmental Law, Vol. 36:2 (2011), p. 309. Available here.
- Id., pp. 272-3.
- Supra at note 3, p. 46.
- Supra at note 12, p. 282.
- Nature, Microsoft’s million-tonne CO2-removal purchase — lessons for net zero (September 29, 2021). Available here.
- Supra at note 9.
- Taskforce on Scaling Voluntary Carbon Markets, New Governance Body Formed to Ensure Integrity of Voluntary Carbon Markets (September 21, 2021). Available here.
- Taskforce on Scaling Voluntary Carbon Markets, Phase 2 Final Report (July 8, 2021). Available here.
Le mois dernier, le Canada a publié sa première Stratégie industrielle de défense (la Stratégie), qui souligne l’engagement du Canada à développer une base industrielle de défense solide et à stimuler la croissance économique. Ces efforts pourraient aussi comprendre le renforcement de l’état de préparation à la biodéfense et aux contre-mesures médicales, ce qui pourrait constituer des débouchés pour le secteur canadien des sciences de la vie en raison de l’importance accordée aux capacités nationales en ce sens et de la nécessité d’atténuer les risques d’urgences sanitaires.
Développement de contre-mesures médicales au Canada
Comme indiqué dans les bulletins précédents, le quatrième pilier de la Stratégie est axé sur la « sécurisation des chaînes d’approvisionnement pour les intrants et les biens clés » par le renforcement de la production nationale et le stockage de ressources. L’accent est mis tout particulièrement sur les contre-mesures médicales, en précisant que nos « alliés ont établi un lien explicite entre l’état de préparation à la biodéfense et aux contre-mesures médicales et leur sécurité économique et nationale, en élaborant de nouvelles stratégies et de nouveaux mécanismes pour faire progresser ces travaux ». Les contre-mesures médicales désignent divers produits réglementés pouvant être utilisés pour protéger la population lors d’une situation d’urgence de grande ampleur, comme l’éclosion d’une maladie ou une attaque impliquant des armes chimiques, biologiques ou nucléaires. Il peut s’agir de vaccins, de médicaments thérapeutiques et produits biologiques, de dispositifs de tests diagnostiques, des équipements de protection individuelle ou industrielle, et d’autres dispositifs médicaux. Les contre-mesures médicales sont essentielles à la réduction et à l’atténuation des dommages lors d’une urgence de santé publique.
Exploiter les voies réglementaires mises en place lors de la pandémie de COVID-19
Pendant et après la pandémie de COVID-19, le Canada a mis en place plusieurs nouvelles voies réglementaires comme mécanismes d’accélération des approbations de produits médicaux, ce qui pourrait offrir au gouvernement des options pour déployer des contre-mesures médicales afin de faire face aux risques pour la santé publique. Au début de la pandémie, Santé Canada a émis diverses ordonnances provisoires pour permettre l’importation et la vente de médicaments et de dispositifs médicaux qui n’avaient pas eu l’approbation des voies réglementaires traditionnelles. Or, Santé Canada a plutôt fait confiance aux voies d’approbation réglementaire et de l’exemption de certaines exigences en homologation de produits des pays impliqués dans la transaction. Beaucoup de ces règles provisoires ont depuis été officiellement intégrées à la réglementation en vertu de la Loi sur les aliments et drogues et ont été appliquées bien après la COVID-19. Conformément au Règlement sur les aliments et drogues, Santé Canada tient à jour la Liste des maladies qui menacent la santé publique et utilisera une procédure d’autorisation modifiée pour les médicaments d’urgence de santé publique pouvant traiter les affections figurant sur la liste. De même, le Règlement sur les instruments médicaux a établi une liste d’instruments médicaux répondant à un besoin urgent de santé publique, ce qui permet à Santé Canada d’autoriser la commercialisation de ces instruments de manière accélérée. Ces outils réglementaires sont utilisés automatiquement quand une situation médicale présente un grand risque pour la santé publique au Canada et nécessite une action immédiate pour contrer ce risque.
Le rôle de la Stratégie dans le renforcement du régime réglementaire de la santé au Canada
La stratégie prévoit que le Canada adoptera une approche proactive en matière de planification en amont des crises sanitaires. Le gouvernement entend s’assurer que les produits médicaux sont déjà disponibles au Canada afin qu’ils puissent être distribués rapidement en cas d’urgence. D’autres modifications récentes au Règlement sur les aliments et drogues permettent de prépositionner au Canada tous les médicaments d’urgence en santé publique, ce qui signifie qu’ils peuvent être importés dans des installations d’entreposage canadiennes avant que leur mise sur le marché n’ait été autorisée. La Stratégie s’appuie sur ces fondements, en faisant référence à l’organisme existant Préparation aux crises sanitaires Canada (PCSC), un organisme opérationnel spécial au sein d’Innovation, Sciences et Développement économique Canada (ISDE), et à un nouveau Fonds des sciences de la vie, lesquels « collaborent avec des partenaires internationaux et de soutenir l’élaboration et la production de contre-mesures médicales ». PCSC supervise la Stratégie en matière de biofabrication et de sciences de la vie du Canada, qui vise à développer un secteur national des sciences de la vie fort et compétitif doté de capacités de biofabrication de pointe, en mettant l’accent sur la capacité à se préparer et à faire face aux futures priorités et crises sanitaires. Dans cette optique, il y aura des occasions pour les fabricants de nouer des collaborations de recherche et des accords commerciaux ou d’approvisionnement liés aux contre-mesures médicales financées par des programmes fédéraux.
Étroitement lié aux capacités nationales, le pilier III de la stratégie implique « Investissement ciblé pour renforcer un secteur canadien de la défense novateur », avec la promesse que le gouvernement fédéral « soutiendr[a] la recherche et le développement, protéger[a] la propriété intellectuelle, soutiendr[a] les petites et moyennes entreprises, investir[a] dans les compétences et la formation, et encourager[a] les exportations afin de créer un secteur de la défense agile et concurrentiel à l’échelle mondiale ». La nécessité de favoriser le développement de la propriété intellectuelle (PI) et la conservation des droits du Canada est mentionnée à plusieurs reprises dans la Stratégie. Par exemple, la Stratégie prévoit l’établissement de partenariats officiels avec l’industrie canadienne qui « [assureront] la propriété et le contrôle nationaux de la propriété intellectuelle (PI) et des capacités essentielles. » La Stratégie reconnaît l’immense talent des établissements canadiens et la précieuse recherche qui y est menée actuellement et qui est déjà financée par des subventions de recherche d’organismes tels que le Conseil de recherches en sciences naturelles et en génie et les Instituts de recherche en santé du Canada, et fait aussi référence à l’engagement de 1,6 milliard de dollars pour de nouveaux fonds de recherche dans le budget de 2025. Cette prise de conscience de la nécessité de promouvoir et de soutenir l’innovation au Canada laisse présager des possibilités de financement, notamment dans les domaines où le Canada accuse un retard en matière de production nationale et où des engagements d’investissement et de fabrication au Canada peuvent être pris.
Prochaines étapes
Dans les prochains mois, nous prévoyons que le gouvernement du Canada publiera d’autres directives et des mesures de suivi. L’équipe de défense des conservateurs poursuivra sa couverture de perspectives sur la défense au Canada en publiant une analyse supplémentaire pour donner des précisions sur l’incidence de la Stratégie sur de multiples secteurs.