BEPS Will Increase Transfer Price Scrutiny
Authors

Tax authorities around the globe remain focussed on profit allocation issues. Under the political banner that each corporation should pay “its fair share” of corporate tax, the final reports from the OECD Base Erosion and Profit Shifting (BEPS) working groups that were released in October1 call for “bold moves by policy makers to restore confidence in the system and ensure that profits are taxed where economic activities take place and value is created.”2 The G20 leaders recently endorsed the BEPS Reports and urged timely implementation in all jurisdictions.
The BEPS TP Reports call for changes to domestic law and to treaty provisions and for the negotiation of a multilateral instrument to be finalized in 2016. More immediately, the BEPS TP Reports introduce changes to the OECD Transfer Pricing Guidelines. Canada generally follows the OECD Transfer Pricing Guidelines, and since Canada has been a leading participant in the BEPS project, we anticipate that the CRA will adopt the new guidelines.
Change has arrived, and taxpayers will now need to evaluate their current compliance, adapt to new rules and be ready for additional implementation issues.
Effects of BEPS
Despite the apparent consensus in the BEPS Reports, each country’s view of “fair share” will be different Paying a “fair share” is a difficult concept in a “rule of law” tax system like Canada whose courts have eschewed “substance over form” in their decisions. Yet transfer pricing is inherently about assessing the relative contributions of local legal entities in a global value chain where increasingly global branding and intellectual property substantially contribute. The BEPS TP Reports call for a portion of an organization’s global profit to be taxed in jurisdictions in which profit arises (i.e., within the market in which the sale is made) or where contributions are made (i.e., the location of labour, intellectual property or capital) as manifested in risk and the ability to control risk. The BEPS Reports have been criticized for their emphasis on “people” contributions over “capital” contributions and for potentially inappropriately skewing residual returns to “people” functions. While the starting place for review remains the contractual relations between the parties, the BEPS TP Reports call for both greater scrutiny of the conduct of the parties and an analysis of risk and control over risk in determining contribution. Taxpayers will be required to maintain an analysis of the “economically relevant characteristics” of the actual transactions in their local transfer pricing file.
Transfer pricing scrutiny will intensify. Global tax authorities, including, in particular, the CRA, have invested considerable resources in audit infrastructure over the past 10 years and these organizations will continue to audit and propose adjustments. There is a political will to be seen to be assessing tax against multinationals. Adjustments are seen as easy pickings. Almost every audit is going to lead to some adjustment–the rules are too imprecise to be able to predict outcomes with certainty. There are a significant number of ongoing Canadian transfer pricing audits that are slowly grinding through the Competent Authority process and others that are making their way into the courts. Appropriate, timely and fair dispute resolution will continue to be a challenge.
Disputes will be inevitable. Despite the clear statements from the Supreme Court of Canada in Canada v. GlaxoSmithKline3 that as long as pricing is within the range of observed comparables, the pricing will be considered to meet the arm’s length standard, in practice, disputes will arise over the selection of methods, the identification of the comparables, the adjustments to be made to comparables and whether (and to what extent) the surrounding facts and circumstances need to be taken into account to derive appropriate pricing. All of this will be analyzed by a government auditor usually with little industry experience and in reliance upon position papers crafted by CRA economists. The BEPS TP Reports will further increase reliance on economic analysis.
The recent BEPS TP Reports will add additional complexity and confusion and which has a negative implication for multinationals through additional exposure upon audit. The BEPS Reports promulgate a risk approach to pricing largely to combat transfer pricing for global products where brand name is important, where multiple teams contribute and where failures are part of the development process. Under that approach, pricing is based on what risks exist and which entity is in the best position to address the risk (i.e., mitigate it, avoid it or absorb it). Data supporting this approach likely do not exist currently, and that rubric will allow multiple approaches from the CRA, leading to increased risk of adjustment. As this risk approach militates toward people functions, it is likely to result in significant interviews of functional staff, and will require greater tracking of people data.
The result will be an increased workload on tax managers in multinational organizations first in compliance and second in defense of the inevitable audits and tax assessments from tax authorities both at home and abroad who seek to collect additional tax. A transfer pricing audit from the CRA will be one of the most expensive and most arduous processes a multinational in Canada will face.
Experience in Canada suggests that resolving transfer pricing issues will be long and difficult. Companies that have outstanding assessments will need to be able to address the implications of a long process. Once an assessment is issued, a large corporation must pay 50% of the tax assessed and file a notice of objection to continue to dispute the assessment regardless of whether dispute follows the Competent Authority or court process. This has an immediate effect on cash flow. It also creates disclosure issues for public companies. We increasingly see transfer pricing as a significant issue in due diligence in corporate finance and M&A transactions. Finally, the pace of change within organizations will affect the ability to contest an assessment. People change, memories fade, and business units are restructured. By the time staff are interviewed they are more focussed on what they do now than able to remember long ago strategies.
Transfer pricing remains at its heart an allocation methodology. Its goal, from a government perspective, is to deliver on corporate tax revenues. This inherently raises double taxation issues and so the domestic audit in many cases quickly leads to Competent Authority processes bilaterally and increasingly to multilateral dispute resolution. This allocation aspect and the use of Competent Authority process takes the audit away from the domestic court process and away from the potential for a principles-based resolution. The nature of negotiation between government tax authorities is more likely to result in compromise than principled outcomes leading to less predictable outcomes.
Be Prepared: Audit Planning
Good advocacy is key to achieving optimal transfer pricing outcomes. Like any dispute resolution method, “prepare, prepare, prepare.”
Below are considerations to keep in mind both in advance of and in response to an audit.
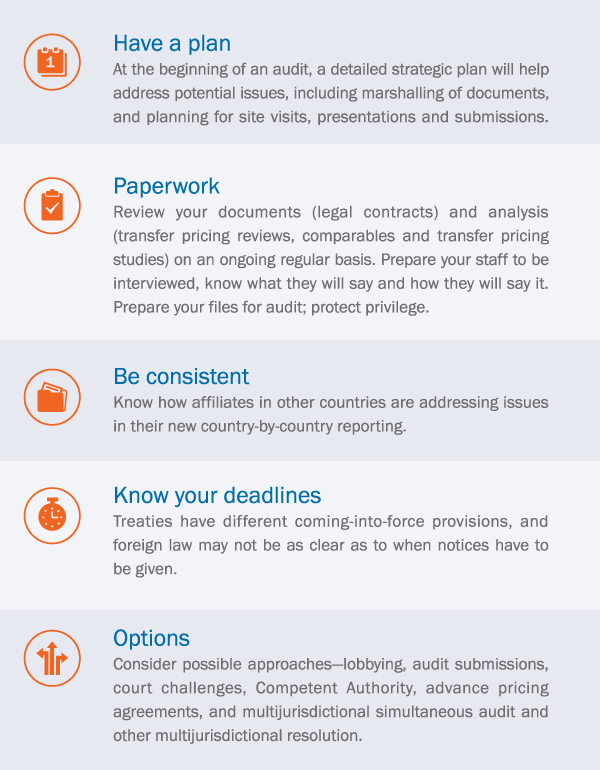
We expect the scope of influence of transfer pricing on corporate decision-making will continue to broaden. Amid the current dynamics of the international landscape, businesses should establish and maintain plans and processes that allow for nimble response to change.
_________________________
1 Final Reports of the Organisation for Economic Co-operation and Development (OECD) Base Erosion and Profit Shifting (BEPS) Action Plans 1 to 15 released October 5, 2015.
2 OECD/G20 BEPS Project; “Aligning Transfer Pricing Outcomes with Value Creation,” Actions 8-10 Final Reports (BEPS TP Reports).
3 2012 SCC 3.
Le mois dernier, le Canada a publié sa première Stratégie industrielle de défense (la Stratégie), qui souligne l’engagement du Canada à développer une base industrielle de défense solide et à stimuler la croissance économique. Ces efforts pourraient aussi comprendre le renforcement de l’état de préparation à la biodéfense et aux contre-mesures médicales, ce qui pourrait constituer des débouchés pour le secteur canadien des sciences de la vie en raison de l’importance accordée aux capacités nationales en ce sens et de la nécessité d’atténuer les risques d’urgences sanitaires.
Développement de contre-mesures médicales au Canada
Comme indiqué dans les bulletins précédents, le quatrième pilier de la Stratégie est axé sur la « sécurisation des chaînes d’approvisionnement pour les intrants et les biens clés » par le renforcement de la production nationale et le stockage de ressources. L’accent est mis tout particulièrement sur les contre-mesures médicales, en précisant que nos « alliés ont établi un lien explicite entre l’état de préparation à la biodéfense et aux contre-mesures médicales et leur sécurité économique et nationale, en élaborant de nouvelles stratégies et de nouveaux mécanismes pour faire progresser ces travaux ». Les contre-mesures médicales désignent divers produits réglementés pouvant être utilisés pour protéger la population lors d’une situation d’urgence de grande ampleur, comme l’éclosion d’une maladie ou une attaque impliquant des armes chimiques, biologiques ou nucléaires. Il peut s’agir de vaccins, de médicaments thérapeutiques et produits biologiques, de dispositifs de tests diagnostiques, des équipements de protection individuelle ou industrielle, et d’autres dispositifs médicaux. Les contre-mesures médicales sont essentielles à la réduction et à l’atténuation des dommages lors d’une urgence de santé publique.
Exploiter les voies réglementaires mises en place lors de la pandémie de COVID-19
Pendant et après la pandémie de COVID-19, le Canada a mis en place plusieurs nouvelles voies réglementaires comme mécanismes d’accélération des approbations de produits médicaux, ce qui pourrait offrir au gouvernement des options pour déployer des contre-mesures médicales afin de faire face aux risques pour la santé publique. Au début de la pandémie, Santé Canada a émis diverses ordonnances provisoires pour permettre l’importation et la vente de médicaments et de dispositifs médicaux qui n’avaient pas eu l’approbation des voies réglementaires traditionnelles. Or, Santé Canada a plutôt fait confiance aux voies d’approbation réglementaire et de l’exemption de certaines exigences en homologation de produits des pays impliqués dans la transaction. Beaucoup de ces règles provisoires ont depuis été officiellement intégrées à la réglementation en vertu de la Loi sur les aliments et drogues et ont été appliquées bien après la COVID-19. Conformément au Règlement sur les aliments et drogues, Santé Canada tient à jour la Liste des maladies qui menacent la santé publique et utilisera une procédure d’autorisation modifiée pour les médicaments d’urgence de santé publique pouvant traiter les affections figurant sur la liste. De même, le Règlement sur les instruments médicaux a établi une liste d’instruments médicaux répondant à un besoin urgent de santé publique, ce qui permet à Santé Canada d’autoriser la commercialisation de ces instruments de manière accélérée. Ces outils réglementaires sont utilisés automatiquement quand une situation médicale présente un grand risque pour la santé publique au Canada et nécessite une action immédiate pour contrer ce risque.
Le rôle de la Stratégie dans le renforcement du régime réglementaire de la santé au Canada
La stratégie prévoit que le Canada adoptera une approche proactive en matière de planification en amont des crises sanitaires. Le gouvernement entend s’assurer que les produits médicaux sont déjà disponibles au Canada afin qu’ils puissent être distribués rapidement en cas d’urgence. D’autres modifications récentes au Règlement sur les aliments et drogues permettent de prépositionner au Canada tous les médicaments d’urgence en santé publique, ce qui signifie qu’ils peuvent être importés dans des installations d’entreposage canadiennes avant que leur mise sur le marché n’ait été autorisée. La Stratégie s’appuie sur ces fondements, en faisant référence à l’organisme existant Préparation aux crises sanitaires Canada (PCSC), un organisme opérationnel spécial au sein d’Innovation, Sciences et Développement économique Canada (ISDE), et à un nouveau Fonds des sciences de la vie, lesquels « collaborent avec des partenaires internationaux et de soutenir l’élaboration et la production de contre-mesures médicales ». PCSC supervise la Stratégie en matière de biofabrication et de sciences de la vie du Canada, qui vise à développer un secteur national des sciences de la vie fort et compétitif doté de capacités de biofabrication de pointe, en mettant l’accent sur la capacité à se préparer et à faire face aux futures priorités et crises sanitaires. Dans cette optique, il y aura des occasions pour les fabricants de nouer des collaborations de recherche et des accords commerciaux ou d’approvisionnement liés aux contre-mesures médicales financées par des programmes fédéraux.
Étroitement lié aux capacités nationales, le pilier III de la stratégie implique « Investissement ciblé pour renforcer un secteur canadien de la défense novateur », avec la promesse que le gouvernement fédéral « soutiendr[a] la recherche et le développement, protéger[a] la propriété intellectuelle, soutiendr[a] les petites et moyennes entreprises, investir[a] dans les compétences et la formation, et encourager[a] les exportations afin de créer un secteur de la défense agile et concurrentiel à l’échelle mondiale ». La nécessité de favoriser le développement de la propriété intellectuelle (PI) et la conservation des droits du Canada est mentionnée à plusieurs reprises dans la Stratégie. Par exemple, la Stratégie prévoit l’établissement de partenariats officiels avec l’industrie canadienne qui « [assureront] la propriété et le contrôle nationaux de la propriété intellectuelle (PI) et des capacités essentielles. » La Stratégie reconnaît l’immense talent des établissements canadiens et la précieuse recherche qui y est menée actuellement et qui est déjà financée par des subventions de recherche d’organismes tels que le Conseil de recherches en sciences naturelles et en génie et les Instituts de recherche en santé du Canada, et fait aussi référence à l’engagement de 1,6 milliard de dollars pour de nouveaux fonds de recherche dans le budget de 2025. Cette prise de conscience de la nécessité de promouvoir et de soutenir l’innovation au Canada laisse présager des possibilités de financement, notamment dans les domaines où le Canada accuse un retard en matière de production nationale et où des engagements d’investissement et de fabrication au Canada peuvent être pris.
Prochaines étapes
Dans les prochains mois, nous prévoyons que le gouvernement du Canada publiera d’autres directives et des mesures de suivi. L’équipe de défense des conservateurs poursuivra sa couverture de perspectives sur la défense au Canada en publiant une analyse supplémentaire pour donner des précisions sur l’incidence de la Stratégie sur de multiples secteurs.
Tags